Compliance
Compliance built in, not bolted on.
- DA and AR wording
- Nothing regulated invented
- Submission handled with you
Everything on a broker’s website is a financial promotion. We build yours that way from the first page, and we work through your network’s review with you.
On the page
Readable, not buried in the small print.
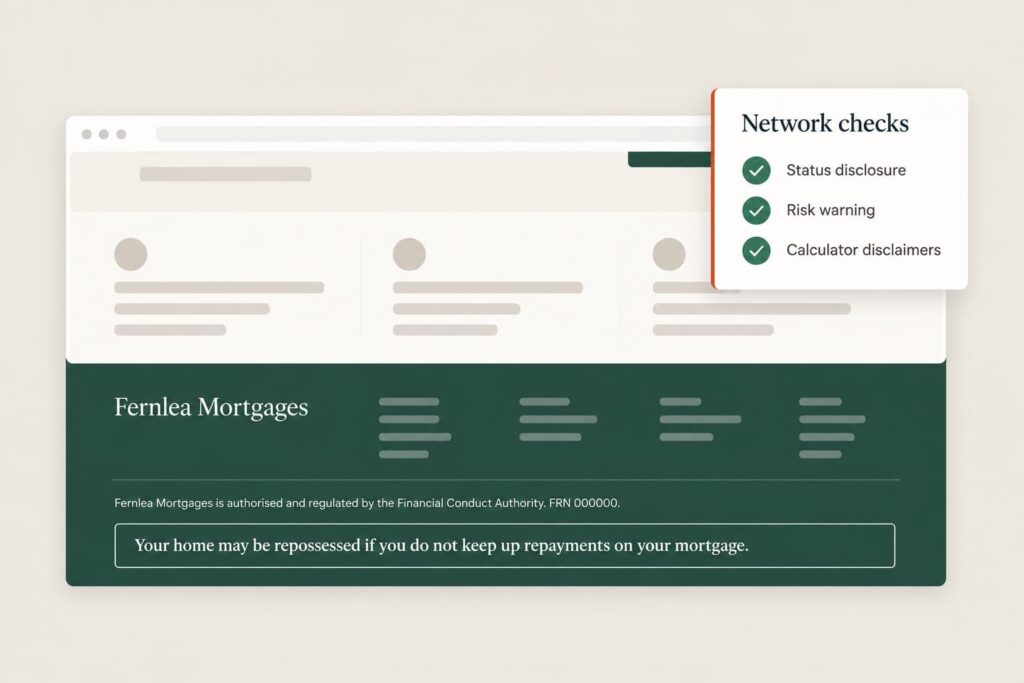
Your status disclosure and risk warnings sit on every page, at a size and contrast people can actually read. That’s what networks look for first, and it’s what your clients are owed.
Your FCA number is entered once and appears everywhere it’s needed. Calculator results print their disclaimer every time, and there’s no setting that switches it off.
Network sign-off
How we get your site approved.
-
01
We ask first
Before we write a word: your status, permissions, fees, lender panel and any wording your network insists on.
-
02
We build to the rules
Disclosures, warnings and plain-English copy in place from the first draft, with placeholders where a fact is still to come.
-
03
We prepare the submission
Your network gets a complete site to review, and we note anything time-sensitive, such as dated figures.
-
04
We make the changes
Whatever your compliance team asks for, we change, and resubmit until it’s signed off. Their word is final.
-
05
We keep it in view
After launch, if an edit needs fresh approval, we tell you before it goes live.
Questions
Compliance questions we get asked.
Yes, and we handle it. An AR’s status disclosure names its principal firm and the principal’s FCA number, and the wording is different from a directly authorised firm’s. We set it up the right way for you, and use your network’s own wording where they have it.
Your network or your compliance officer. We prepare everything they need and make the changes they ask for, but the approval is theirs and so is the final say.
Their wording wins, every time. Send it to us and we’ll use it exactly as written.
Yes. An ad for mortgage advice is a financial promotion, just like your website. We write the ads to the same rules and work with your compliance network to get them signed off before they run.
Yes, as long as they’re real, current and linked to where they came from. We never write or pad reviews: fake reviews are unlawful, and your network would find them.