Mortgage calculators
Six mortgage calculators, on every plan.
- Included on every plan
- Disclaimers can’t be switched off
- Stamp duty for all UK regions
Borrowers run the numbers before they pick up the phone. Give them the tools on your site, not a comparison site’s, with the disclaimers built in.
What’s included
Place any of them on any page.
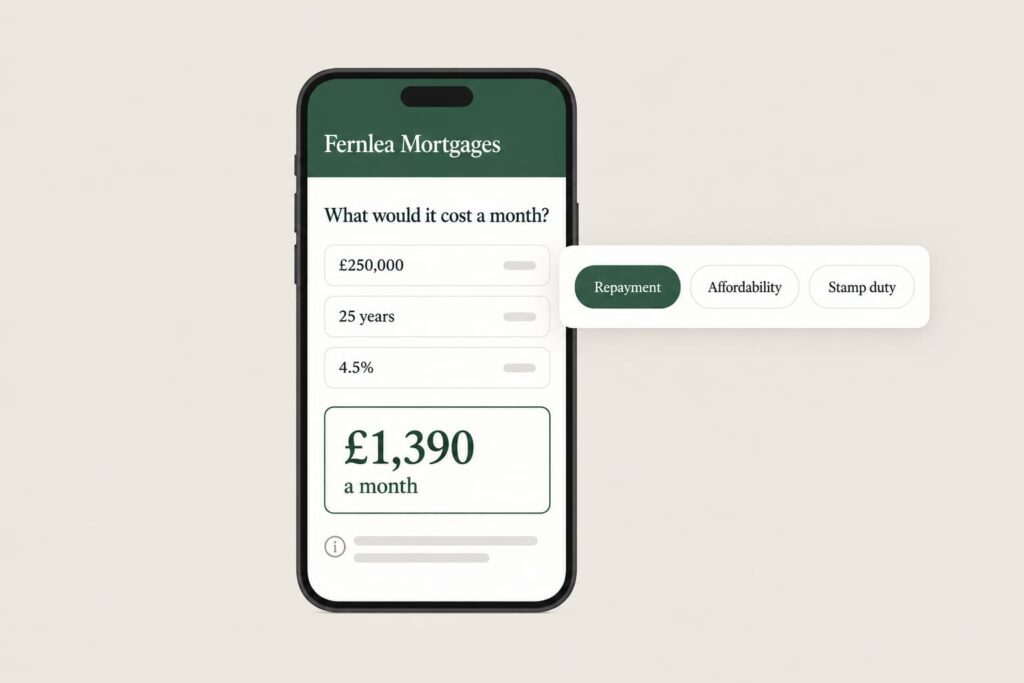
- Repayment: what a mortgage would cost a month, with the capital and interest split.
- Affordability: the range a lender might consider, as a range, never a promise.
- Stamp duty: SDLT for England and Northern Ireland, LBTT for Scotland and LTT for Wales, with the rate tables kept up to date for you.
- Overpayment: what paying a little more would save.
- Rate change: a new rate against the current one, for remortgage conversations.
- Interest-only compared: both ways, side by side.
Every result prints the disclaimer and the right risk warning, and there’s no setting that removes them. If your network wants extra wording, it goes underneath. Try three of them below.
Repayment
What would it cost a month?
The one most visitors reach for first. Change the figures and the disclaimer travels with the result.
Your figures
Left blank on purpose — we do not publish a rate. Use a figure you have been quoted, or ask an adviser what you might be offered.
Estimate
Enter an interest rate
The loan and the loan to value are worked out below. Add a rate to see the monthly payment.
- You'd borrow
- £255,000
- Loan to value
- 85%
- Total interest
- —
- Paid over the term
- —
What this assumes
- The same interest rate for the whole term. Most deals are fixed for two to five years, then move.
- No arrangement, valuation, legal or broker fees, and no early repayment charge.
- Every payment covers interest and capital, so the balance falls each month.
These figures are an estimate only and are not a quote, an offer of credit or financial advice. The calculation assumes the same interest rate applies for the whole term and does not include fees, insurance or other costs. Your actual payments will depend on the product you're offered, your circumstances and the lender's assessment. Speak to an adviser for a personalised illustration.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Affordability
How much might a lender consider?
Shown as a range with the income multiples printed beside it, so it never reads as a promise.
Income and commitments
We are not asking about dependants, your job, your credit history or what you spend. A real affordability assessment covers all of it, and a form that asked would only look like one.
Estimate · a rough guide only
Add an income to begin
Nothing you type here is sent anywhere or stored.
- With the deposit, a price around
- —
- Deposit
- —
- Multiples used
- 4× to 4.5×
- Loan to value at the top
- —
Lenders typically consider somewhere between 4 and 4.5 times a household's annual income, after regular credit commitments. Every lender does it differently, and income multiples are only part of an assessment — affordability, credit history, the property and the product all change the answer.
This is not a mortgage offer, a decision in principle, or advice about what you should borrow.
What this assumes
- Income multiples of 4 to 4.5 times, applied after twelve months of the credit commitments entered.
- That the income entered is gross, regular and can be evidenced. Bonus, commission and self-employed income are all treated differently by lenders.
- No stress test, no credit scoring and no look at spending — all three are part of a real lending decision, and none of them are here.
These figures are an estimate only and are not a quote, an offer of credit or financial advice. The range is worked out from income multiples alone, and does not look at your outgoings, your credit history, the property or the product. Any amount a lender would actually offer depends on the product, your circumstances and the lender's assessment. Speak to an adviser for a personalised illustration.
Your home may be repossessed if you do not keep up repayments on your mortgage.
Stamp duty
What tax is due on the purchase?
England and Northern Ireland, Scotland and Wales, each with its own rates. We keep the tables up to date for you.
The purchase
Estimate · SDLT due
£5,000
Payable within 14 days of completion. Your conveyancer normally handles it.
- Property price
- £300,000
- Effective rate
- 1.67%
- Price plus tax
- £305,000
How the £5,000 is worked out
Each slice of the price is taxed at its own rate, and the slices are added together.
| Slice of the price | Rate | Taxable in this band | Tax |
|---|---|---|---|
| £0 to £125,000 | 0% | £125,000 | £0.00 |
| £125,000 to £250,000 | 2% | £125,000 | £2,500.00 |
| £250,000 to £300,000 | 5% | £50,000 | £2,500.00 |
| Total | £5,000 | ||
What this assumes
- A straightforward residential purchase by an individual.
- Where a surcharge applies, that any other property you own is worth £40,000 or more. The calculator cannot know that, so it goes by what you tell it.
- Purchases through a company, trusts, mixed-use property and multiple dwellings all work differently.
This is a guide to the tax payable on a residential purchase in England & Northern Ireland, worked from the rates shown. It is an estimate, not a calculation of your liability, and it does not cover every relief or surcharge. Purchases through a company, trusts, mixed-use property and multiple dwellings all work differently. Your conveyancer will confirm what is actually payable.
Your home may be repossessed if you do not keep up repayments on your mortgage.
SDLT rates correct as at 20 September 2026. Checked against gov.uk.
Questions
Calculator questions.
They’re built to. Each result is labelled as an estimate, says it isn’t a quote, an offer or advice, states its assumptions and prints the risk warning. Your network still reviews them like the rest of your site, and any wording they add goes beneath the disclaimer.
No. Gating a basic number behind a form is a Consumer Duty problem, so results are always free to see. Each calculator has a button to get in touch when they’re ready.
We do. The rate tables are part of the platform and are updated when the rates change, across every site at once.
You can, but a rate is a cost figure and brings in extra requirements, so it needs your network’s sign-off first. By default the rate field opens empty and the visitor enters their own.